Santa Clara County (SCC): Median Home Sales Price Sets New Record
The median sales price for single-family, re-sale homes was up 3.1% compared to last year. The median sales price set a new record high of $2,166,120.
The average sales price for single-family, re-sale homes was up 3.4% year-over-year. The average sales price was $2,522,990.
Sales of single-family, re-sale homes were down 17.7%, year-over-year. There were 700 homes sold in Santa Clara County last month. The monthly average since 2000 is 987.
The sales price to list price ratio fell from 107.5% to 104.5%.
Pending sales were down 2.6% year-over-year. There are 682 homes in escrow.
Inventory of single-family, re-sale homes was up 39.3% compared to last year. As of June 5th, there were 1,035 homes for sale in Santa Clara County. The average since January 2000 is 2,703.
Days of Inventory, or how long it would take to sell all homes listed for sale at the current rate of sales, rose from 38 days to 44 days. The average since 2003 is 89.
It took seventeen days to sell a home last month. That is the time from when a home is listed for sale to when it goes into contract.
The median sales price for condos was down 10.3% compared to last May. The median sales price was $970,000. The average sales price fell 6% year-over-year. The average sales price was $1,075,860.
Condo sales were down 2747%. There were 267 condos sold in May.
The sales price to list price ratio fell from 102.8% to 101.7%.
Pending sales were down 3.9% year-over-year. There are 299 condos in escrow.
Condo inventory was up 66% compared to last May.
As of June 5th, there were 674 condos for sale in Santa Clara County. The average since January 2000 is 757.
Days of inventory rose from sixty-five to seventy-six.
It took an average of twenty-four days to sell a condo last month.
If you are planning on selling your property, call me for a free comparative market analysis.
May 2025 Sales Statistics (SCC)

* Total inventory is active listings plus pending listings. Active listings do not include  pending.
More information is available in our on-line report at http://avi.rereport.com/market_reports

Uncertainty Delays Opportunity (SCC & SMC)
May 30, 2025 — Since the announcements of significant tariffs on U.S. trading partners, rather a lot has changed. Advance ordering to avoid expected higher costs distorted the calculation of first quarter GDP, turning it negative, even though underlying economic fundamentals still seem solid enough. Even so, worries about a future downturn became elevated. Consumer and business moods turned truly dark and inflation expectations spiked. Overarching these and other issues is a broad sense of uncertainty, as expectations for trade policy and any ultimate impact on inflation and the broader economy continue to evolve, seemingly as often as every day.
That’s unfortunate, since absent the upheaval the imposition of new or expanded levies we’d likely be in a situation where solid growth amid fading inflation might have seen the Fed feeling comfortable about making a cut to short-term interest rates at the coming June meeting. However, with the on-again, off-again, larger-then-smaller (and larger again?) nature of the imposition of new tariffs, there’s simply no way for the Fed or anyone else to develop a good sense of what the outcome will be. As such, the Fed is resigned to holding policy steady and waiting for clues and signs.
Consumer Confidence rose 12.3 points to 98.0 in May, its best showing since February. Current conditions were assessed to be somewhat more favorable, posting a 4.8 point gain to 135.9 while the outlook enjoyed a greater burst of optimism, powering 17.4 points higher to rise to 72.8 for the month. Inflation expectations here also moderated a bit, with the May expectation halving the increase over the last two months, and the half-point decline leaving it at a flat 6.5%. Consumer plans to buy new vehicles pushed higher, reaching their highest mark since last May, while those to buy homes rebounded to a level last seen in December 2022. The increase in plans to buy a home in the Conference Board’s survey seems rather at odds with other observations. Of course, plans to do something aren’t exactly a firm commitment, either. Firm commitments come in the form of signed contracts to buy, and unfortunately, there were rather fewer of those in April. The National Association of Realtors Pending Home Sales Index (PHSI) declined by 6.3% in April, and this decline will impact existing home sales figures for May and June. We discussed the spring housing market in last week’s Market Trends, and it doesn’t look as though the start of the summer will be much improved.
New applications for mortgage credit slid again in the week ending May 23. The Mortgage Bankers Association reported a 1.2% decline in requests for mortgage funds, with the top-line figure pulled down by a 7.1% reduction in applications to refinance existing mortgages but lifted by a 2.7% increase in those for funds to buy homes. Perhaps some of the optimistic planners in the Conference Board’s survey decided to jump in, after all.
More folks would jump in to the market if mortgage rates were more favorable, but conditions just don’t support those at the moment. Absent all the tariff uncertainty there would still be concerns about deficits and debts, budgets and more, but the outlook for the economy and inflation would probably not be among them. Modest growth and easing price pressures are a recipe for the Fed gradually moving policy back toward a neutral stance, and such signals would help longer-term rates to find at least some space to gradually decline.
Unfortunately, those days and times aren’t now, and uncertainty is preventing the opportunity for lower interest rates to help energize the housing market. Perhaps the dust will settle somewhat as the summer progresses, and the size and shape of the levies will become better known; if so, this may allow for monetary policy to start to be adjusted gradually downward. This would be far preferable to the outcomes the Fed’s staff outlined in the minutes. Until then, we’ll just wade through and wait out the uncertainty.
Mortgage rates will likely retreat a little next week, at least based on market conditions at the end of this one. However, the decline will probably be only enough to erase this week’s modest increase or perhaps a little more. The data spigot opens full blast again next week with the first-of-the-month cascade, but surprises (if any) seem more likely to be to the downside than up. As such, we think that the average offered rate for a conforming 30-year fixed-rate mortgage as reported by Freddie Mac will decline by 4-6 basis points.
Call or email me if you have any questions.
For further details and a city-by-city breakdown statistics, go to http://avi.rereport.com/market_reports.


Real estate related Articles
| MarketWatch 4-30-2025 | 10 housing markets in the U.S. with the most price cuts right now |
| J.P. Morgan 2-10-2025 | The outlook for the US housing market in 2025 |
| SJM 3-6-2025 | Silicon Valley’s inequality gap is Silicon Valley’s inequality gap is growing twice as fast as in rest of U.S. |
| Palo Alto Online 2-28-2025 | Silicon Valley house hunters face toughest market in 50 years |
California homeowners interested in building accessory dwelling units on their property just caught a break, potentially shaving off thousands of dollars in fees and permits.
In a move proponents say will help ease the Bay Area’s housing crisis, Gov. Jerry Brown on Tuesday signed Senate Bill 1069, making the so-called “granny units” easier and less expensive to build throughout the state.
For more read California eases restrictions on ‘granny units’ and http://www.hcd.ca.gov/policy-research/AccessoryDwellingUnits.shtml
Helpful resource for home owners
Many new home owners or owners who consider remodeling or rebuilding their homes should take advantage of their county Tax Assessor web site. These web site and their respective city building departments web site typically have vest information regarding the process for applying for permits, the impact on their taxes and many other resources that home owners should be aware are available for them.
For the San Mateo County Tax Assessor office visit http://www.smcare.org/default.asp
For Santa Clara County Tax Assessor visit https://www.sccassessor.org/index.php
The Silicon Valley 150 Index Corner
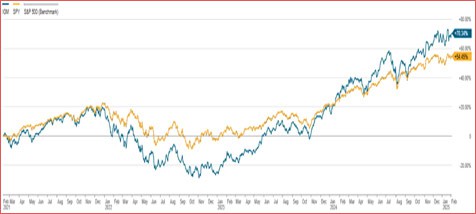
The Silicon Valley’s Real estate market is a derivative of the local economy–it prospers and withers depending on how well the local innovation-based sector performs. The San Jose Mercury News tracks the performances of the largest 150 publicly traded companies headquartered in Silicon Valley through an index called the SV150, which may be found at www.mercurynews.com. Stocks are valued based on several criteria, but one of the more important criteria is a company’s future earnings. Therefore, I see the SV150 as a leading indicator for Silicon Valley’s real estate market.
Investors Corner
S&P CoreLogic Case-Shiller Index Records 3.6% Annua Gain in October 2024
NEW YORK, DECEMBER 31, 2024: S&P Dow Jones Indices (S&P DJI) today released the October 2024 results for the S&P CoreLogic Case-Shiller Indices. The leading measure of U.S. home prices recorded a 3.6% annual gain in October 2024, a slight deceleration from the previous annual gains in 2024. More than 27 years of history are available for the data series and can be accessed in full by going to CLICK HERE
U.S. Housing Markets Moving Into Rent Territory for First Time in Over 8 Years: Report
Is it time to seriously consider investing in real estate?
Signup for my Real Estate Investment Alerts and you’ll receive my real estate investment opportunities.
San Mateo County (SMC): Home Prices & Sales Up in April
Sales of single-family, re-sale homes in San Mateo County rose 5.4% in April, year-over-year. There were 291 homes sold in San Mateo County last month. The average since 2000 is 398.
The median sales price for single-family, re-sale homes was $2,226315,000. It was up 7.8% compared to last year.
The average sales price rose 7.5% year-over-year.
The sales price to list price ratio fell from 108.1% to 106.8%.
Inventory of single-family, re-sale homes was up 25.4% compared to last year. As of May 5th, there were 429 homes for sale in San Mateo County. The average since January 2000 is 1,287.
Days of Inventory, or the amount of time it would take to sell all homes for sale divided by how many homes have sold, fell from forty-seven days to forty-three days.
It took nineteen days, on average, to sell a home last month. That is the time from when a home is listed to when it goes into contract.
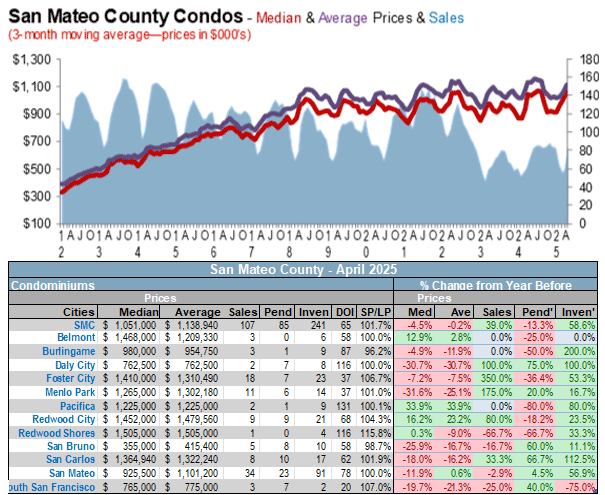
The median sales price for re-sale condos fell 4.5% year-over-year.
Year-over-year, the average sales price fell 0.2%.
Condo sales were up 39% year-over-year. There were 107 condos sold last month. The average since January 2003 is 122.
Inventory was up 58.6% year-over-year.
As of May 5th, there were 241 condos for sale in San Mateo County. The average since January 2003 is 350.
Days of inventory fell from seventy-three to sixty-five.
It took an average of twenty-one days to sell a condo last month.
If you are planning on selling your property, call me for a free comparative market analysis.
May 2025 Sales Statistics (SMC)

* Total inventory is active listings plus pending listings. Active listings do not include pending.
You can get more information at: http://avi.rereport.com/market_reports


Call or email me if you have any questions.
For further details and a city-by-city breakdown statistics, go to http://avi.rereport.com/market_reports.